

Money Network® Mobile App
Fiserv, Incorporated
- 3.1
- 36.10K Reviews
- 5.00M
- Downloads
- Free
- Price
Screenshots
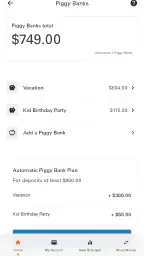
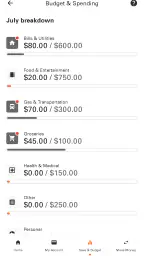
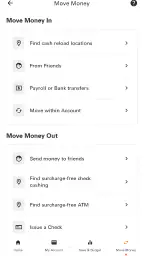
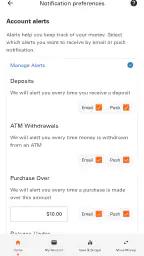
Money Network® Mobile App Pros and Cons
Pros
- Quick access to balance, transactions, and available funds
- Mobile check deposit can reduce the need to visit a bank
- Card controls help users manage security and spending
- Push alerts can notify you about purchases and account activity
- Useful for managing employer-provided or prepaid Money Network funds
Cons
- Some features may depend on your card type or program eligibility
- Identity verification can be required before accessing certain services
- Prepaid accounts may include fees for selected transactions or services
- Support options and response times may vary by account program
- The app is less useful if you do not have an eligible Money Network card
 Analysis by All-app
Managing money on a shared phone is a surprisingly delicate task. A household may use one device to check a balance, confirm whether a payment arrived, or review recent activity, yet a financial app should never be treated like a shared notebook. After spending time with Money Network® Mobile App, I found that its main value is straightforward access to a Money Network account, while its real test is whether each person can keep their account activity separate and private.
For a first-time user, I would set expectations around one clear purpose: mobile access to a Money Network account. This is not the place I would look for a household budget or a combined view of several banks. It is a free finance app from Fiserv, Incorporated, rated for Everyone. It has been available since March 26, 2013, and its current version is 20.0.1. The app has attracted more than five million installs, with an average rating of 3.1 from roughly seventy-two thousand ratings and about thirty-six thousand written reviews. Those numbers suggest a widely used service with a noticeably mixed experience, so I would approach it as a practical account-access tool rather than an app that will impress everyone.
Using it on a shared household device
The most realistic household scenario is simple: one family member needs to check a Money Network balance while the phone is already being used by someone else. Perhaps a parent is helping a young adult confirm available funds before buying groceries, or two adults are coordinating a household expense. The app can make that moment quicker than opening a browser and searching for the account page, but the convenience depends heavily on keeping the right person in control of the session.
I would not leave the app open on a shared device after checking an account. A balance and transaction history are personal financial details, even when the phone belongs to the household. My practical routine would be to open the app only when the account holder is present, finish the check, sign out if that option is available for the account, and close the app before handing the phone to another person. I would also avoid saving credentials where another household member can reach them.
That boundary matters more than the app’s simple interface. A shared phone does not automatically make an account shared, and this service should not be used as a substitute for a joint financial arrangement. If several people need ongoing access, I would first make sure each person understands whose account is being viewed and who is responsible for any action taken inside it.
One useful habit is to separate “checking” from “acting.” Looking at a balance may be a quick household coordination task, but changing account details or initiating a financial action deserves a private moment with the account holder. This reduces the chance of tapping the wrong option while someone is asking questions, rushing through a checkout line, or passing the phone around.
What setup feels like in practice
Because Money Network® Mobile App is focused on Money Network account information, the setup is best approached as an account-access process rather than a general budgeting installation. I would have the account holder complete the initial sign-in personally, keep account credentials out of group chats and notes, and make sure the device itself is protected with a screen lock. Those steps are not flashy, but they are especially important when a phone is used by several people.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would also decide in advance who is allowed to use the app. In a couple, one person might help with a balance check but not handle the other person’s account independently. In a household with older children, a parent may demonstrate the app while the child remains responsible for entering credentials and reviewing the information. This creates a clearer boundary than simply saying, “You can use my phone.”
The app is free, which removes a purchase decision, but free does not mean frictionless. A user still needs a Money Network account and must be comfortable handling personal financial information on a mobile device. Someone looking for a complete household budget, shared bill calendar, or combined view of multiple unrelated accounts will probably find that this is the wrong category of tool.
My advice is to install it for the person who actually owns or manages the Money Network account, not automatically for every member of the household. If another person needs information, the account holder can show the relevant detail directly when appropriate. This keeps the app’s purpose narrow and avoids turning a private account into an informal family dashboard.
Coordinating money without mixing accounts
The app is most useful when coordination requires a quick answer. Before leaving a store, a user can check whether the expected funds are available. Before dividing a household purchase, the account holder can review recent activity and confirm what has already cleared. These are small moments, but they are exactly where a dedicated account app is more convenient than relying on memory.
There is a trade-off, though. A balance check tells you what is visible in the account, but it does not replace a household plan. I would still use a separate shared note or conversation for who is buying supplies, who has already contributed, and which expenses belong to which person. Keeping those coordination details outside the financial account makes responsibilities clearer and avoids giving everyone unnecessary access.
A second practical tip is to verify the account identity before discussing a number aloud. On a shared phone, it is easy to assume the last session belonged to the right person. I would pause, confirm the account holder, and only then review the information. This is particularly important when two adults use the same device or when one person helps another with several financial apps.
For a household that needs a broader picture, a traditional banking app or a dedicated budgeting service may be better. Those alternatives are designed around categories, recurring expenses, or multiple accounts. Money Network® Mobile App has a narrower job: giving its account holders mobile access to their Money Network information. That focus is useful when speed matters, but limiting when the household wants planning tools.
I also would not treat the app as a replacement for statements or careful record keeping. For a disputed transaction, a reimbursement discussion, or a larger household decision, I would record the relevant details separately and keep the account holder involved. The app can help you see information; it does not remove the need for judgment.
Age, trust, and responsibility
The Everyone age rating makes the app broadly approachable, but that should not be confused with independent financial readiness. A younger user may be able to understand a balance screen while still needing an adult to explain available funds, pending activity, and the consequences of sharing login details. I would introduce the app as a way to view one’s own account, not as a game-like tool for experimenting.
Trust is more important than age alone. A trusted family member might help with navigation, but I would avoid asking someone else to remember credentials or routinely operate the account without supervision. The cleanest arrangement is for the account holder to remain the person who signs in, checks the details, and decides what action to take.
This also matters for shared devices used by guests, roommates, or caregivers. A household can be close without having identical financial rights. If another person needs to help because of accessibility, travel, or a time-sensitive purchase, I would agree on the exact task beforehand and take the phone back once that task is complete.
One limitation I noticed from this perspective is that the app’s usefulness depends on users creating their own boundaries. It should not be installed with the assumption that a family will receive built-in household supervision or a shared family workspace. I would choose it for direct account access, not for managing children’s spending or assigning permissions among relatives.
For someone who is uncomfortable using financial information on a phone, the mobile format may also feel like a disadvantage. A browser or another account-access method can be preferable when the user wants a larger screen, a more deliberate review, or less temptation to check financial details casually in public. The best choice depends on whether convenience outweighs that preference.
Where the app fits among finance alternatives
Compared with a general banking app, this service is more specialized. Its appeal is that a Money Network user can keep account information close at hand instead of treating mobile access as an occasional desktop task. Compared with a budgeting app, it is less about analyzing an entire household’s finances and more about checking the account connected to the service.
That distinction helped me decide who should use it. I would recommend it to a Money Network account holder who regularly needs quick mobile access and wants a free option dedicated to that account. I would be more cautious with someone searching for bill reminders, shared envelopes, spending charts, investment tracking, or a unified view of several financial institutions.
The rating of 3.1 indicates that the experience is not universally smooth, and the large volume of written feedback reinforces the need for realistic expectations. I would keep the app updated, use a stable connection when checking important information, and avoid waiting until a checkout or urgent payment moment to discover that access is not working as expected. A backup way to reach the account is sensible for anything time-sensitive.
Another trade-off is convenience versus concentration. A dedicated app can reduce steps for a frequent account check, but it also encourages users to rely on one mobile route. If the phone is lost, shared, unavailable, or being repaired, the household should not be left without a plan for accessing important financial information. That is not a reason to avoid the app; it is a reason not to make it the only method anyone knows.
Making the first useful check count
For a newcomer, I would choose a calm moment for the first sign-in rather than trying to learn the app while standing at a checkout. Have the account holder’s information ready, use a private setting, and take enough time to recognize the account details once access is established. The first useful success is modest: confirming that the account opens and locating the information you came to check. That small test is more reassuring than relying on the app for an urgent purchase before you know how it behaves on your device.
After that initial check, I would make a simple personal routine: open the app when there is a specific question, review the relevant information, then close the session. This keeps quick access from turning into casual browsing of sensitive details on a phone that other people may handle. If the account holder is helping someone else, they can read the information themselves and share only what the other person needs to know.
A common point of confusion is treating a displayed balance as a complete household spending answer. It can help with a decision in the moment, but the household may still need to account for planned purchases, shared contributions, or activity that has not yet been reflected as expected. I would use the app to check the account, then use a separate conversation or record for the group’s plan. That division makes it easier to distinguish account information from household agreements.
Another question first-time users often have is whether the app is suitable for everyone in the family simply because its age rating is Everyone. I would not read that rating as permission for everyone to share one login. The account holder should remain in charge of access, and anyone offering help should know exactly what they are being asked to do. If a user is not comfortable handling financial information on a phone, a browser or another account-access route may feel more deliberate.
For the everyday grocery example, I would check the account before leaving home if the purchase depends on available funds, rather than making the first attempt in a busy queue. If the app is unavailable or the displayed information does not answer the question, having another way to access the account prevents one mobile session from becoming the sole point of failure. That backup habit is especially useful for people who depend on timely access but do not want to share credentials with someone else.
The right next step after a successful check is to decide what you actually need from a finance app. If your regular task is viewing information tied to a Money Network account, this focused tool may be enough. If your aim is to track spending across several institutions, organize bills with another person, or build a longer-term budget, I would choose a service designed around those jobs instead. Keeping that distinction in mind makes it easier to judge the app on its real purpose rather than on features it is not meant to provide.
My household verdict
After using Money Network® Mobile App as a finance utility, I see it as a focused and potentially handy companion for the right account holder. Its strongest quality is directness: it is built around mobile access to Money Network account information rather than trying to become a complete financial planning system. For a person who checks an account frequently, that narrow purpose can be exactly what is needed.
I would recommend it to an individual or household member who understands account privacy, uses a protected device, and wants a free mobile option for routine checks. I would not recommend treating it as a shared family wallet, a parental-control system, or a replacement for a household budget. Those expectations lead to disappointment because they go beyond the app’s central role.
My final advice is to make account boundaries part of the setup: the owner signs in, helpers assist only when invited, and everyone knows when the session is finished. Used that way, the app can make everyday coordination less awkward without blurring who owns the information. If your needs are broader than checking one Money Network account, a full banking or budgeting alternative will likely serve you better.
Frequently Asked Questions
What is the Money Network® Mobile App used for?
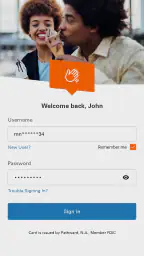
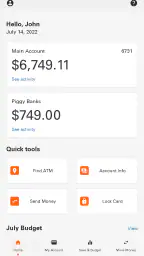
The Money Network® Mobile App is designed to help eligible cardholders manage their Money Network account from an Android or iOS device. After signing in, users can generally review their available balance, view transaction history, receive account notifications, locate participating ATMs, and manage certain card settings. The exact tools available may depend on the card program, employer, benefits provider, region, and account type.
How do I sign in or activate my Money Network account?
To use the app, you normally need an eligible Money Network card or account and the login details created during registration. New users may be asked to enter card information, personal verification details, and a security code before creating credentials. If activation or sign-in fails, check that your information matches the card records and use the official recovery options rather than repeatedly entering incorrect details.
Can I use the app to check my balance and transactions?
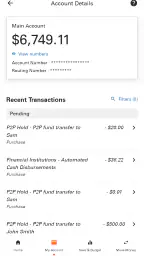
Yes, checking account activity is one of the main reasons to use the Money Network Mobile App. The balance screen can help you confirm available funds, while transaction history may show purchases, deposits, withdrawals, fees, and other account movements. Keep in mind that balances and pending transactions may not update instantly, so the app should not always be treated as a real-time guarantee.
Does the Money Network® Mobile App charge fees?
Downloading the Money Network Mobile App is generally free, but using the related account or card may involve fees depending on the specific program and transaction type. Possible charges can include out-of-network ATM withdrawals, replacement cards, expedited services, or other account activities. Review the fee schedule connected to your card before relying on a particular feature, and remember that your mobile carrier may charge data fees.
Is the Money Network Mobile App safe to use?
The app includes standard account-security measures such as login protection, verification procedures, and the ability to monitor transactions from a mobile device. For safer use, download it only from the official Google Play or Apple App Store listing, avoid sharing passwords or verification codes, enable device security features, and sign out on shared devices. Contact official support immediately if you notice unauthorized activity.


